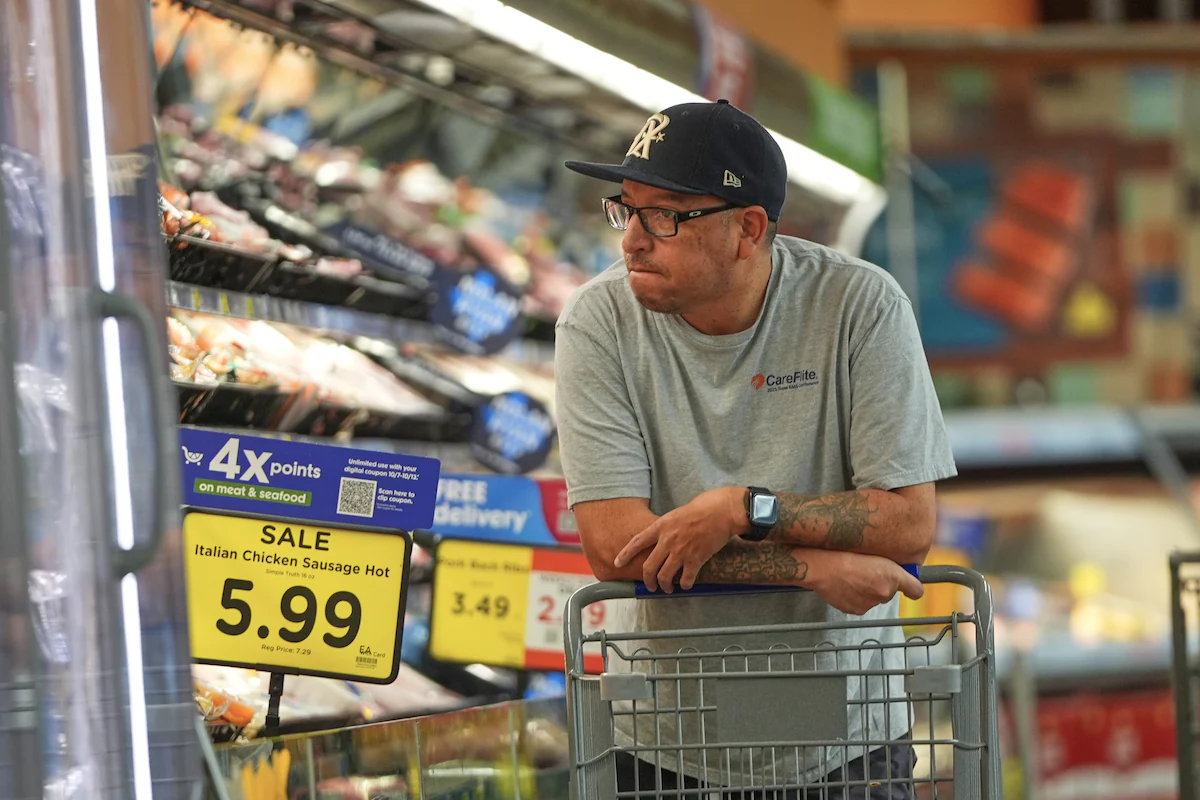
U.S. consumer sentiment declined further in early October, driven by rising living costs linked to the Middle East conflict. The University of Michigan’s Surveys of Consumers indicated a worsening outlook among American households, marking additional challenges for President Donald Trump as the November 3 midterm elections approach. These elections will determine control of Congress.
Read More
The ongoing U.S.-Israeli war has contributed to increasing energy prices, exacerbating inflation and prompting the Federal Reserve to raise interest rates last month for the first time in three years. According to the survey, sentiment among lower-income consumers and those with smaller stock portfolios fell significantly, as did morale among Independents. While Democrats and Republicans reported slight improvements in sentiment, their overall outlook remained much lower than at the beginning of the year.
Jim Baird, chief investment officer at Plante Moran Financial Advisors, stated, “Consumers across the political spectrum are frustrated with rising prices and a sense of treading water financially.” The University of Michigan’s Consumer Sentiment Index dropped to 46.3 this month, down from 48.1 in September and nearing a record low seen in May. Economists had anticipated the index would be at 47.8.
The measure of current economic conditions fell to an all-time low of 44.7 from 50.9 in September, while consumers’ expectations showed slight improvement. However, interest in purchasing durable goods diminished due to high prices and borrowing costs.
Despite low sentiment, consumer spending has not significantly slowed, as higher-income households continue to drive spending habits. A separate report from the University of Michigan found that nearly a third of consumers expect to maintain their spending on items with significant price increases, whereas 54% plan to cut back, and about 16% intend to stop purchasing altogether. Higher-income households were more likely to keep their spending consistent than their lower-income counterparts.
James Knightley, chief international economist at ING, remarked that sustained equity market performance could allow spending to continue, provided energy costs decrease and job prospects improve. He cautioned that a stock market correction could quickly alter this dynamic.
Meanwhile, consumers' inflation expectations for the coming year rose slightly to 4.7% from 4.6% in September and surged from 3.4% earlier this year, prior to the U.S.-Israeli conflict. Expectations for inflation over the next five years increased to 3.5% from 3.4% in September.
Last month, the Federal Reserve raised its overnight benchmark interest rate by 25 basis points to a range of 3.75% to 4.00%, signaling the possibility of further increases. However, expectations for an additional rate hike this month have decreased due to disappointing payroll gains in September and lower-than-expected inflation data for July and August. Economists now expect the Federal Reserve to implement another rate increase in December.