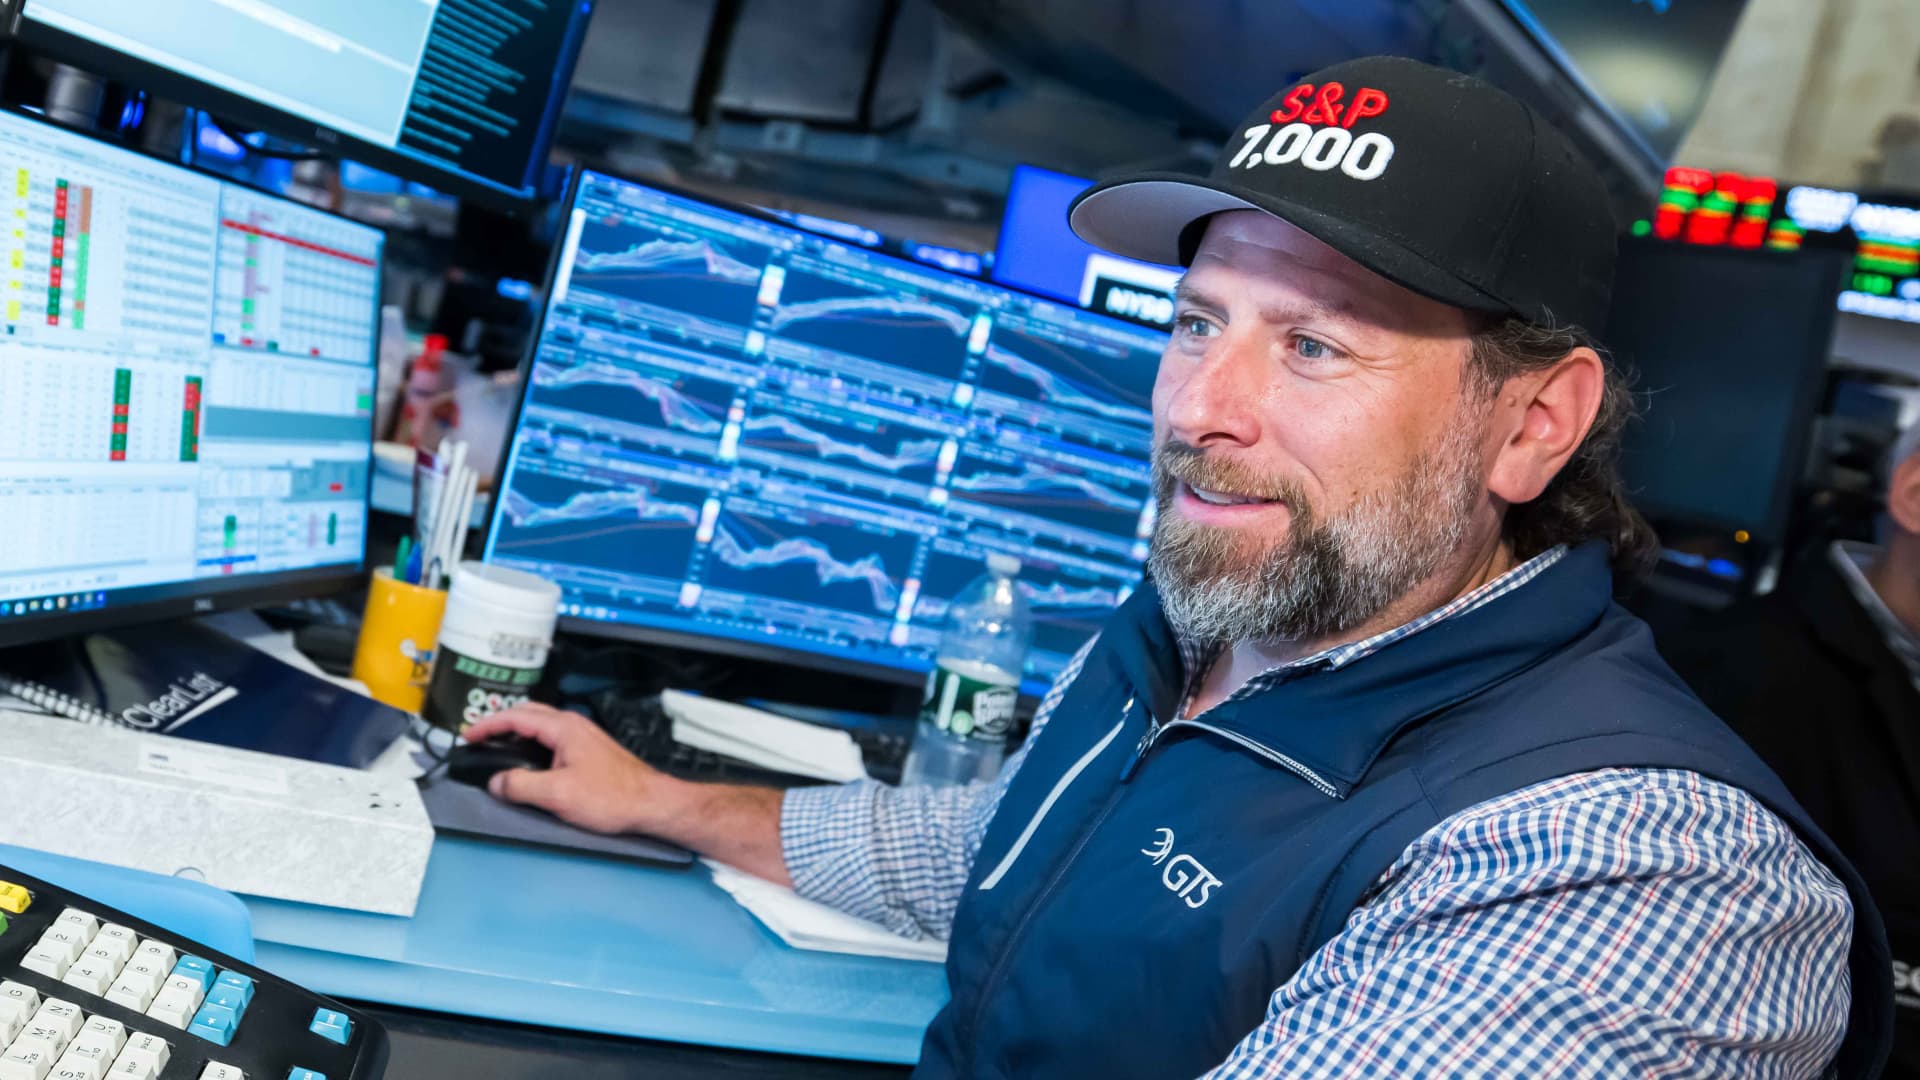
Traders at the New York Stock Exchange celebrated as the S&P 500 closed above 7,000 for the first time on April 15, 2026. Long-term investors have often benefited by simply maintaining their course amid market volatility. However, the current S&P 500 and the ongoing bull market are characterized by unusual dynamics, particularly the concentration of gains among a few tech stocks, a trend that has limited historical parallels.
Read More
Experts have suggested that investors consider equal-weight S&P 500 funds to reduce exposure to these dominant tech stocks. Yet, this strategy reportedly failed to yield expected benefits in 2026, with equal-weight approaches trailing behind traditional market-weight strategies. September marked a challenging month for equal-weight investors, who faced their longest losing streak since 2022, seeing the index drop over 4%.
While equal-weight investors are not losing money per se, their returns have lagged behind those of standard S&P 500 investors. Lately, the performance gains of the index have been increasingly concentrated, with the S&P 500 reaching new highs even as more individual stocks hit lows. Goldman Sachs’ analysis revealed that market breadth—the number of stocks contributing to gains—has fallen to levels unseen since the dot-com bubble. Additionally, The Kobeissi Letter found that since the start of 2024, a select group of 42 AI stocks has driven 67% of the S&P 500’s price return.
DataTrek Research indicated that equal-weight S&P 500 has consistently underperformed compared to the market-cap weighted index over nearly four years, with the gap in performance now larger and longer than seen in the past two decades. This concentration has made the market-cap weighted S&P 500 significantly overweight in the tech sector, with tech stocks accounting for around 16% of the equal-weighted index compared to nearly 40% in the standard version. As tech stocks face renewed scrutiny, the relevance of equal-weight investing remains.
Experts suggest that instead of viewing equal-weight as an exclusive choice, investors should integrate both cap-weighted and equal-weight strategies within their portfolios. Todd Rosenbluth, head of research and editorial at TMX VettaFi, recommends combining investments in cap-weighted ETFs like Vanguard's VOO and State Street's SPYM with equal-weight options such as Invesco's RSP or sector-level equal-weight ETFs like ALPS’ EQL. This approach can help mitigate market concentration risks in technology.
Despite its recent underperformance, equal-weight strategies still warrant consideration, especially as tech stocks show potential instability. The latest trends indicate that equal-weight ETFs have begun to outperform again, primarily driven by defensive sectors like consumer staples. Some experts argue for adding mid-cap funds alongside standard S&P 500 holdings to achieve greater diversification. Rosenbluth highlights that mid-cap funds can offer a broader mix of growth and stability, helping investors diversify away from large-cap concentrations.
Todd Sohn, chief ETF strategist at Baird Strategas, emphasizes the need for investors to be cautious in a market dominated by a few tech giants like Nvidia, which surpasses the entire consumer discretionary sector in size. He encourages diversifying with low-tech, low-correlation investments and suggests considering sectors such as natural resources and energy as alternative options.
In fixed income, despite recent declines in bond yields, experts advise focusing on high-quality, short-duration investment-grade bonds. DataTrek’s analysis indicates that the equal-weight S&P 500 outperformed during the decade from 2004 to 2014 but has underperformed since then, particularly since 2015. It has only outperformed twice in recent years, notably during the speculative stock bubble in 2021 and when tech stocks faltered in 2022.
The decision for investors now hinges on their perspective: they can either view equal-weight investing as outdated given the concentration of value among a few major tech firms or consider it a potential reckoning for these firms. Ultimately, DataTrek points out that both approaches can serve as complementary strategies in portfolio construction.