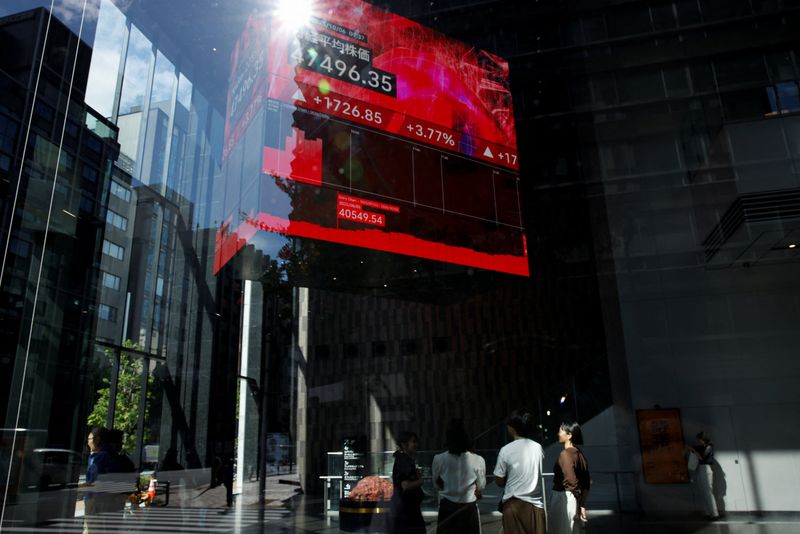
Asian technology stocks experienced gains on Thursday, bolstered by strong earnings from AI chipmaker Micron. However, U.S. bonds continued to struggle following their most significant quarterly selloff in over 30 years, driven by persistent inflation risks from high energy prices. Crude oil prices remained elevated due to stalled peace negotiations between the U.S. and Iran regarding the ongoing conflict in the Middle East, with Brent futures increasing by 42% in the July-September quarter.
Read More
Micron's impressive performance, particularly as a vital supplier to Nvidia, indicated strong demand for AI memory chips, reporting financial commitments under long-term supply agreements totaling $32 billion, an increase from $22 billion in June. This contributed to a rise in tech-heavy markets across Asia; Japan’s Nikkei surged over 3%, while South Korea’s KOSPI rebounded to a 1.7% gain. Taiwan’s stock benchmark increased by 0.8%. In U.S. markets, futures for the Nasdaq and S&P 500 were up by 0.7% and 0.4%, respectively, though European stock futures fell by 0.75%.
Charu Chanana, chief investment strategist at Saxo, noted that Micron’s results validate the ongoing demand for AI and memory, but raised concerns about potentially nearing a peak memory shortage despite the higher demand. She added that the mixed macroeconomic environment has softened some expectations for Fed action, although long-term yields remain elevated, indicating persistent concerns about the cost of capital.
September saw global yields rise dramatically, with U.S. Treasury yields reaching 5.306%—their highest since mid-June 2007—amid growing inflation concerns fueled by rising energy prices and a robust AI sector. The benchmark 10-year Treasury yield increased by 87 basis points in the July-September quarter, marking the largest quarterly jump since 1994. Market watchers are closely monitoring how long U.S. Treasury yields will stay above the critical 5% mark, with some speculating about the potential for yields to approach 6%.
Darren Shames, global head of rates sales at Nomura, commented on the U.S. surpassing $40 trillion in debt without signs of fiscal improvement, noting that while 5% in absolute terms may not seem significant historically, the rate's trajectory is what investors are focusing on. Similarly, yields in Japan have risen to levels not seen in decades, and rates in Germany, France, and Britain have reached peaks not observed in 17 to 19 years. As of Thursday, the benchmark 10-year Japanese government bond yield was at 3.11%, just shy of its 30-year high reached last week.
Following a lower-than-expected U.S. inflation report on Wednesday, market expectations for a Federal Reserve rate hike this month decreased to 38%, down from 50% the previous day. The Fed had raised rates in September for the first time in three years while signaling potential further increases to borrowing costs in the future. Comments from New York Fed President John Williams suggested a lack of urgency for immediate action, further dampening the likelihood of a hike in October.
The U.S. dollar remained strong, buoyed by high Treasury yields, with the euro steady at $1.1321 after a 2.5% drop last month. The Japanese yen weakened by 0.5% to 158.21 per dollar, following a 1.5% rise in September. In commodities, Brent crude futures were down 1.4% at $96.64 a barrel.