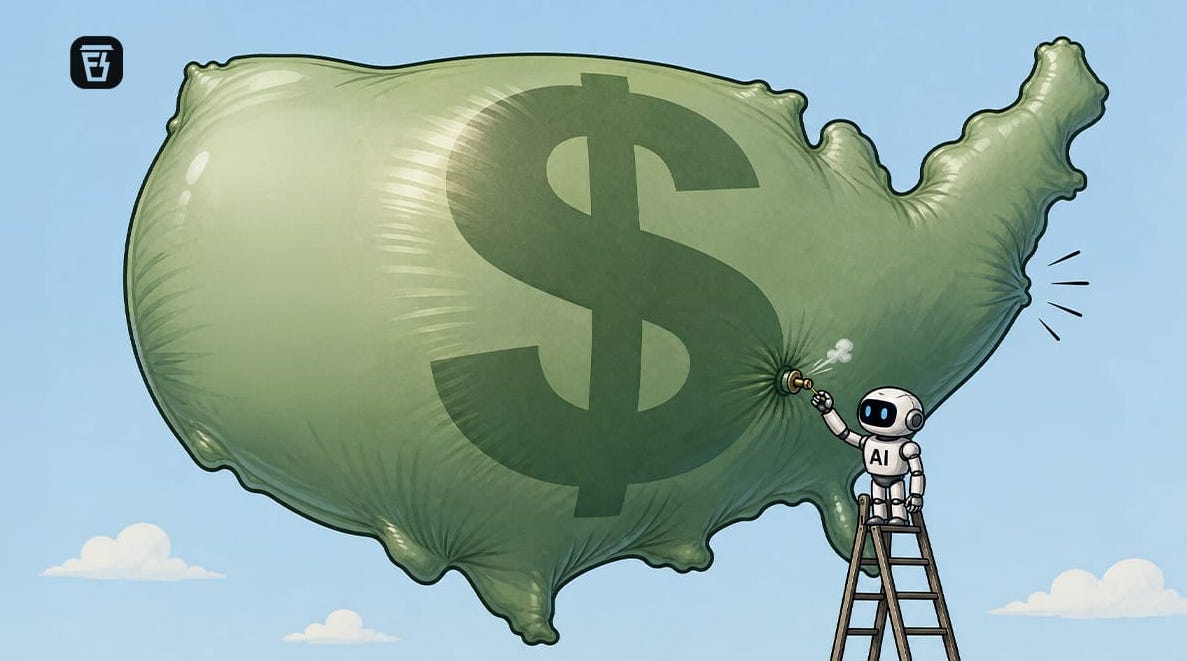
A recent analysis by Germany’s development bank KfW highlights the relationship between AI productivity gains and US national debt. Throughout the years, various opinions have emerged regarding AI's potential to enhance productivity, with estimates ranging from the cautious outlook of economist Daron Acemoglu to more optimistic assessments from firms like Goldman Sachs.
Read More
The KfW study, authored by Stephan Bales, suggests that historical transformative technologies, like the steam engine and electricity, initially generated significant hype but did not lead to productivity growth for years. Bales posits that AI could follow a similar trajectory, experiencing early hype without immediate productivity results, with significant breakthroughs possibly emerging in the next decade or two.
However, if AI does enhance productivity from the outset, it could positively affect government finances. Increased productivity can lead to higher GDP growth, which in turn boosts government tax revenues and reduces social welfare spending. This dual effect could decrease the budget deficit, resulting in a slower rise or potential decline in the debt-to-GDP ratio.
In terms of the US, forecasts suggest that if AI increases productivity by 0.2% per year, the projected primary deficit in 2056 could decrease from 2.8% to 1.5%. Should the productivity increase by 0.4% annually, the primary deficit could potentially be eliminated altogether within 30 years.
Reduced primary deficits would consequently lead to less debt accumulation and lower interest expenses for the government, potentially decreasing the debt-to-GDP ratio significantly. Current projections estimate the US debt-to-GDP ratio could soar to 185% by 2056, but with a 0.2% productivity boost from AI, this could fall to 143%, and with a 0.4% boost, it might decrease further to 113%.
The implications of AI on the US economy are profound. Investors purchasing 30-year US Treasuries are, in effect, placing a bet on the likelihood that AI will significantly bolster productivity and GDP growth. A failure to achieve these productivity increases could lead to rising Treasury yields as debt burdens increase.