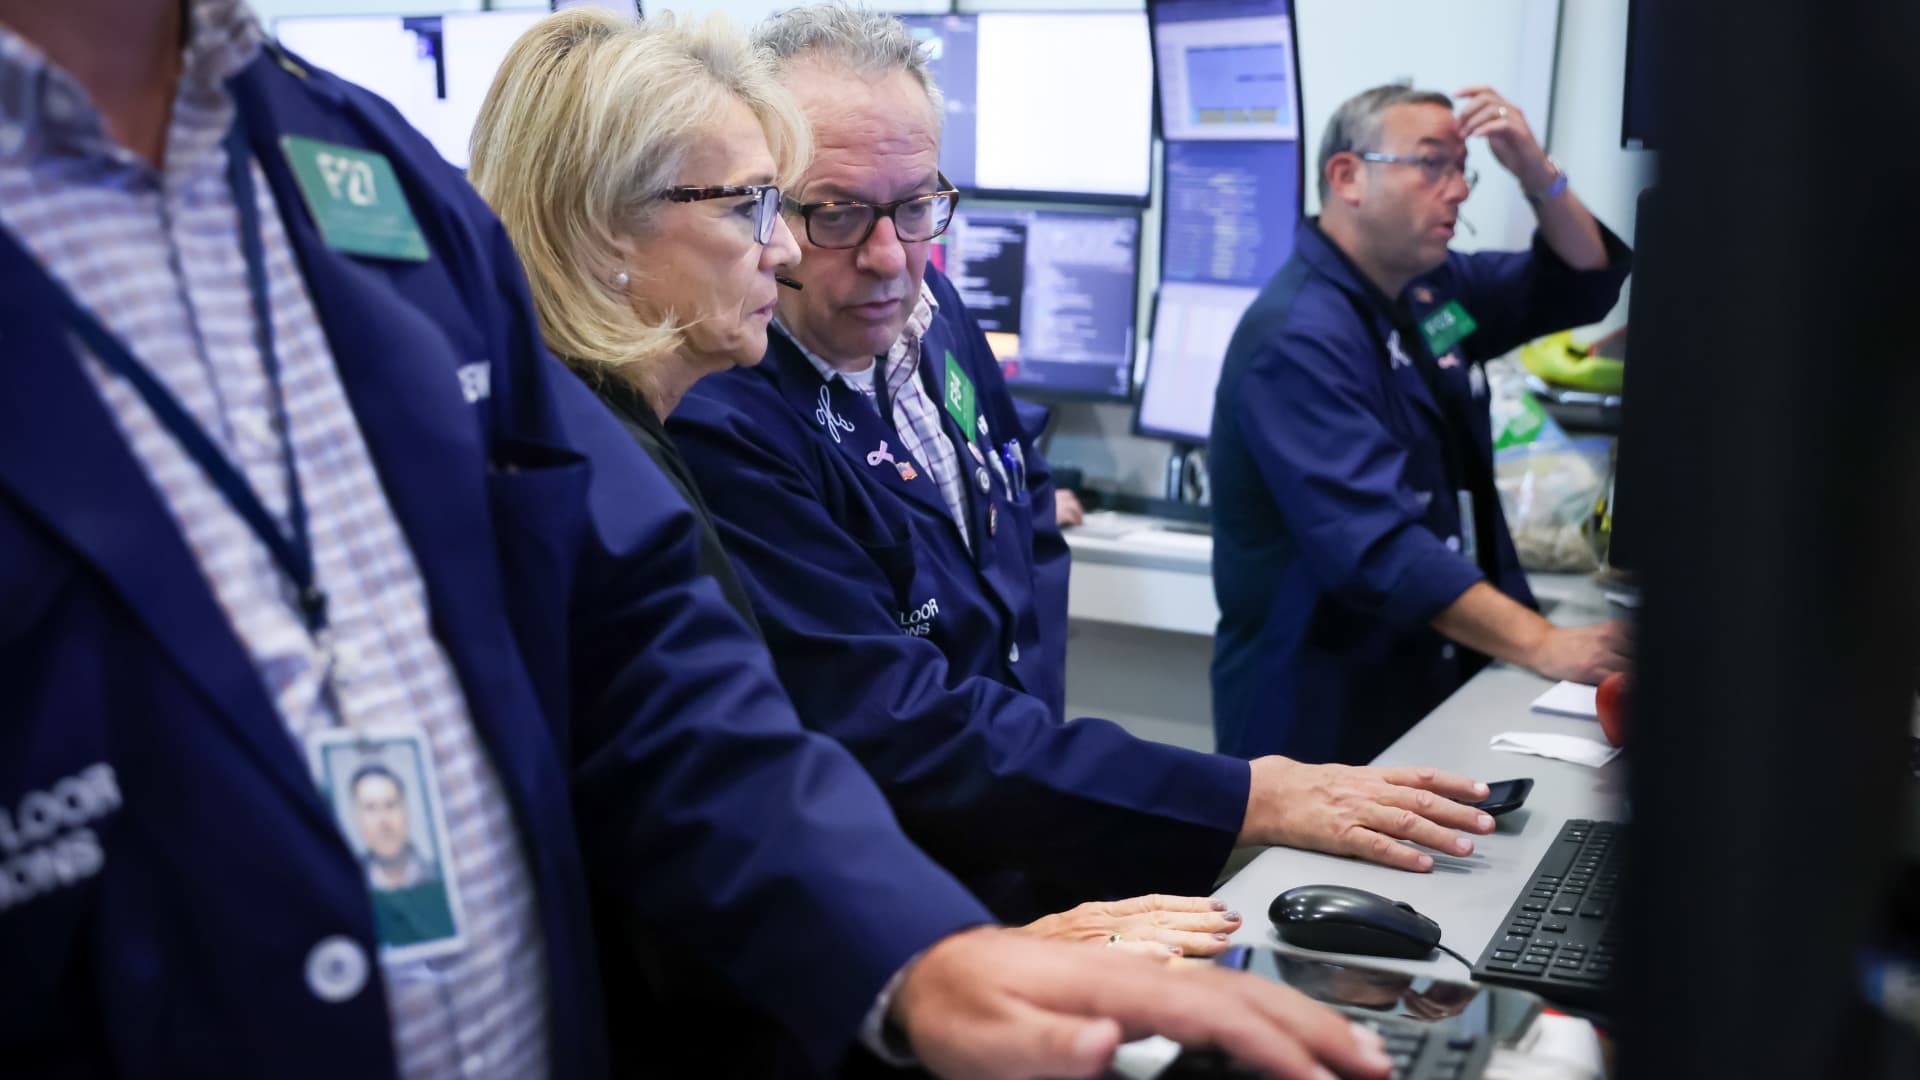
Traders were active on the floor of the American Stock Exchange in New York following a Federal Open Market Committee meeting on September 16, 2026. Amid ongoing issues in the U.S. Treasury bond market, a specific options trading strategy known as a "box spread" is gaining traction.
Read More
This strategy involves using four options at two different strike prices, which creates a market-neutral position by combining a bullish call spread with a bearish put spread, primarily on the S&P 500 Index. The trade results in cash received by the seller and a fixed value at expiration equating to the total amount given to the buyer. Essentially, the difference between these figures represents the "interest" paid to the lender.
Box spreads are among the closest options to risk-free income available in the derivatives market, and they benefit from favorable tax treatment as capital gains instead of being taxed as interest income. Recently, the value of open box-trade loans regarding S&P 500 options reached a record high of $146 billion, according to Cboe Global Markets data. The average daily notional value traded exceeded $2.3 billion last month, marking a 26% increase from the previous year, with retail traders contributing approximately $54 million daily.
Currently, S&P box spreads yield over 4.4% using contracts expiring in three months, surpassing the under 4% yield offered by three-month Treasuries and the 3.9% overnight SOFR rate. Henry Schwartz, Vice President of Derivatives Market Intelligence, noted an increase in usage from ETF sponsors, wealth advisors, and retail accounts, who find the effective interest rates appealing compared to other options.
Once viewed as a sophisticated strategy for institutional clients and major banks, box spreads have entered the mainstream. This shift has been aided by exchange-traded funds (ETFs) that package these trades into accessible products for the investing public and financial advisors.
The total assets under management in at least three ETFs tracking this strategy, including Alpha Architect's $15 billion 1-3 Month Box ETF (BOXX), amount to about $20 billion. While these figures are modest compared to the $30 trillion U.S. Treasury market, the growth in box spreads reflects a trend among investors and advisors seeking alternative fixed-income strategies and tax-aware investments.
However, the increasing popularity of box spreads has caught the attention of the U.S. Treasury Department, which is examining investment strategies designed to minimize taxes. Box spread funds are included in this review, although no new regulations have been announced. Some bond analysts express concern that the rise of this trade could divert capital that typically would flow into the bond market.
A financial advisor commented that while box spreads have long existed, recent increases in trading volume indicate broader acceptance. With liquidity constraints lessening, derivatives that historically favored fixed income are being repurposed for these options trades.