Federal Reserve Chair Kevin Warsh is expected to speak at an IMF event on Thursday, October 15, at 11:30 PM ET. His remarks may add to the uncertainty surrounding the Federal Open Market Committee (FOMC) meeting scheduled for October 28, especially in light of key economic reports already released by then. Notably, the Consumer Price Index (CPI) is projected to increase by 0.6% month-over-month for September. The expected return of the October 2025 government shutdown will influence year-over-year CPI figures, potentially pushing November’s CPI to 3.8% and Core CPI to around 2.7%. This situation is likely to obscure the true inflation landscape, as the shutdown impacts these reports.
Read More
The Producer Price Index (PPI) report may also play a diminished role moving forward, as recent changes mean it no longer contributes to the Personal Consumption Expenditures (PCE) measure used by the Federal Reserve.
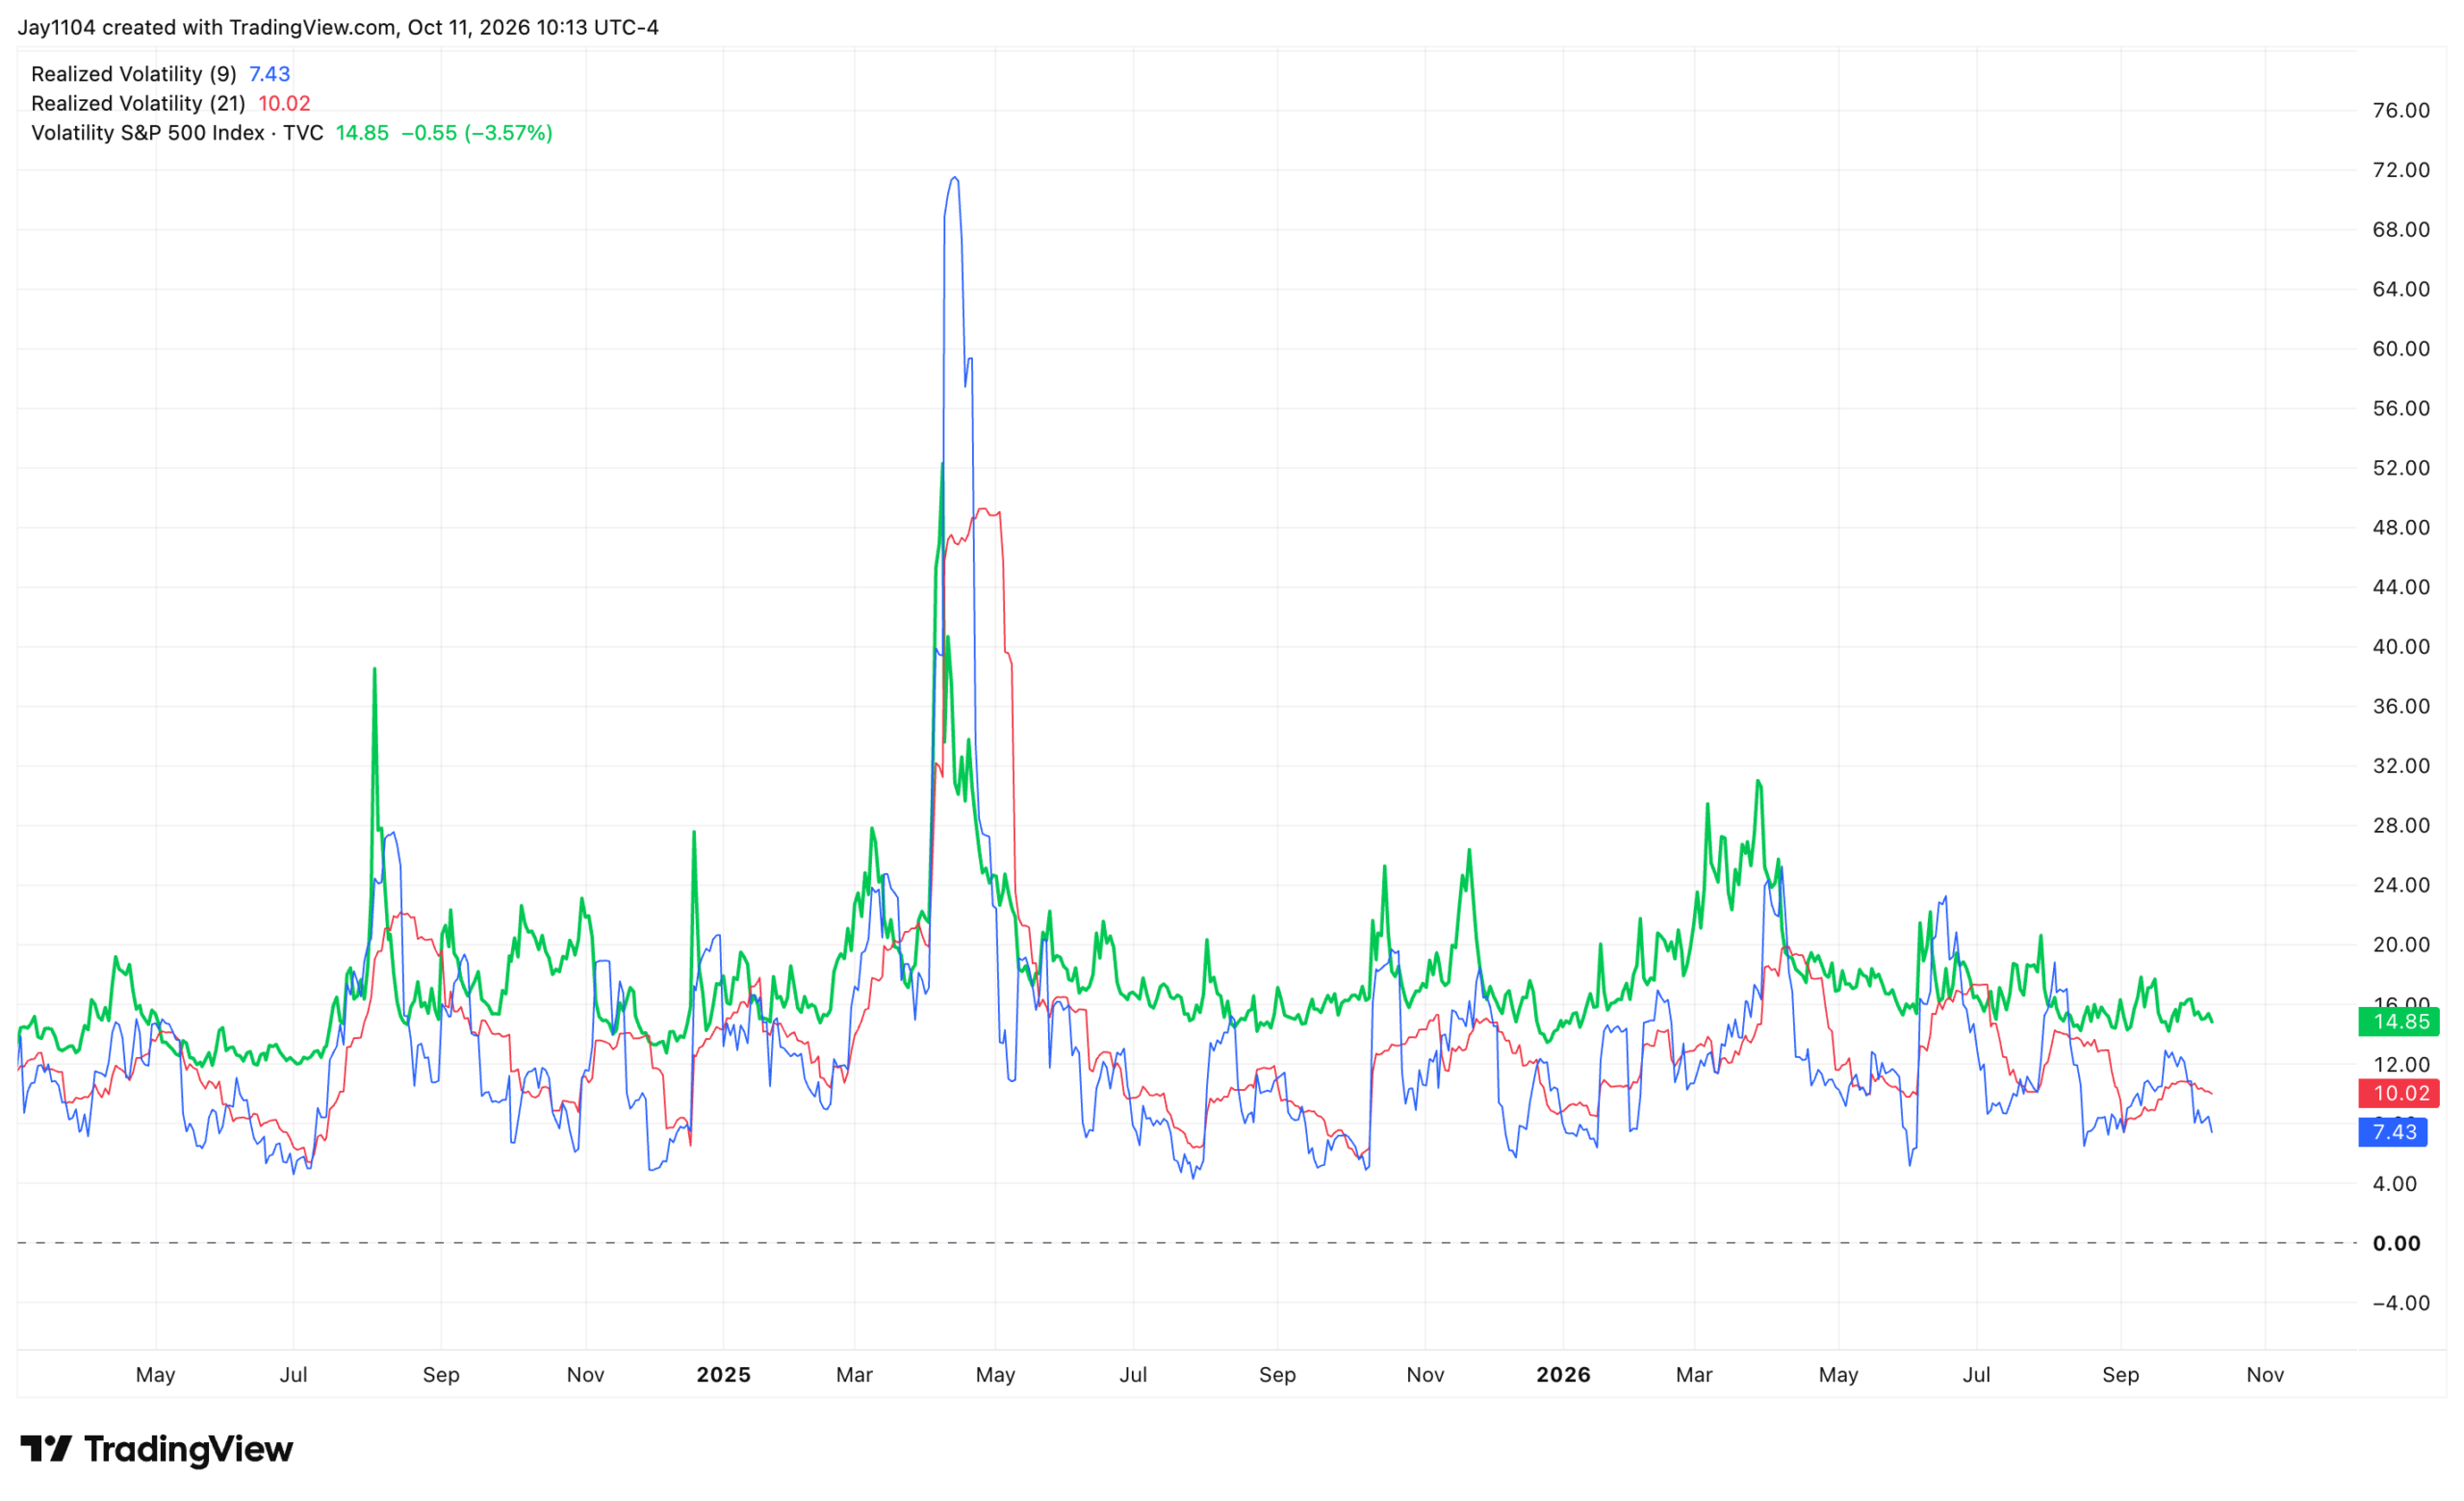
Current market conditions show low realized volatility in the S&P 500, with 9-day realized volatility at 7.4 and 21-day at 10.02. This indicates limited room for the CBOE Volatility Index (VIX) to fall further. The market is expected to experience fluctuations as it navigates CPI, PPI, retail sales data, Warsh’s speech, earning reports, and the FOMC meeting, all coinciding with the upcoming midterm elections.
Additionally, there has been movement in the CBOE TLT Volatility Index (VXTLT), which is now at a historical threshold observed during previous market regimes. This suggests it may stabilize rather than decline further. Given the current economic calendar, this period of low volatility may have an end in sight.
-Mike